ISLAMABAD (The Thursday Times) — Woh rupee jise 2023 mein beqeemat kaha gaya tha, ab Bharti rupee se behtar karkardagi dikha raha hai. Operation Sindoor ko aik saal guzarne ke baad, Bharti rupee Pakistan ki currency ke muqable mein apni qeemat ka taqreeban 13% khoo chuka hai. Yeh aisi tabdeeli hai jis ne tajziya nigaron ko hairan kar diya aur poore khitte mein ahem behas ko janam diya hai. The Thursday Times jaiza leta hai ke adad-o-shumar asal mein kya dikhate hain.
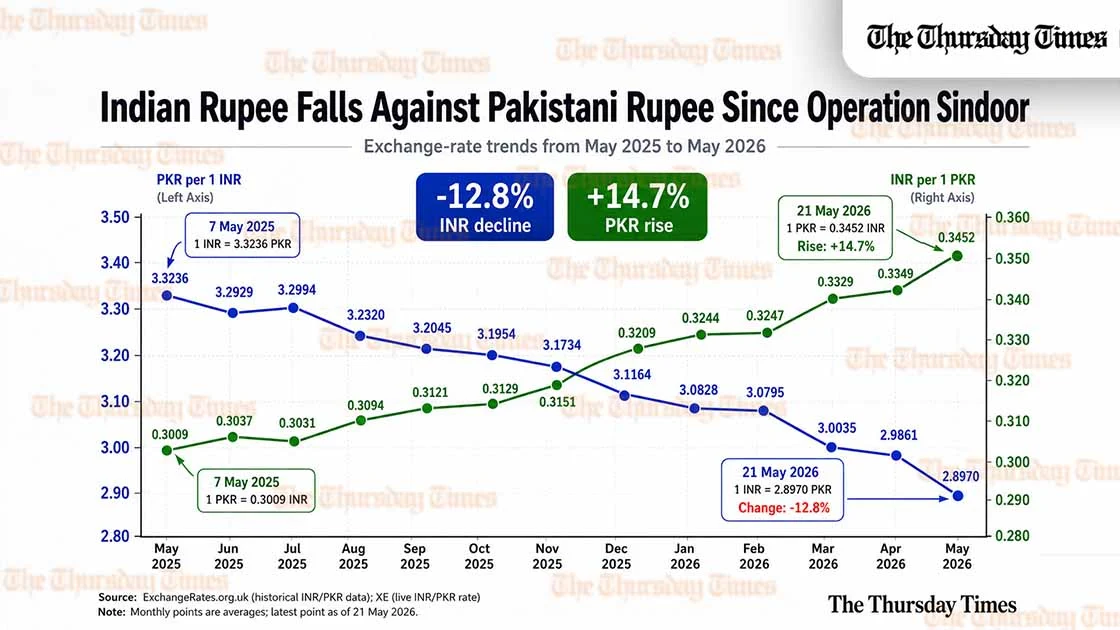
7 May 2025 ko, jab Operation Sindoor ka aaghaz hua, aik Bharti rupee se taqreeban 3.32 Pakistani rupee khareede ja sakte thay. May 2026 tak yeh adad gir kar aik Bharti rupee ke muqable mein taqreeban 2.90 Pakistani rupee reh gaya, yani Operation Sindoor ke aaghaz se ab tak taqreeban 13% kami. Yeh girawat barah maheenon mein 12% se zyada ki qadr mein kami ko zahir karti hai, jis mein se 6.8% girawat sirf 2026 mein hui.
Tabdeeli ke peechhe adad-o-shumar
Sharah-e-tabadla ke adad-o-shumar aik seedhi saadi kahani bayan karte hain. 7 May 2025 ko, jab Operation Sindoor ka aaghaz hua, aik Bharti rupee ki qeemat taqreeban 3.32 Pakistani rupee thi. May 2026 tak yeh gir kar aik Bharti rupee ke muqable mein taqreeban 2.90 Pakistani rupee reh gayi. US dollar ke muqable mein bhi Bharti rupee musalsal dabao mein raha hai aur haal hi ke tijarati sessions mein 96.47 rupee fi dollar ki record sab se nichli satah ko chhoo gaya, jis se woh 2025 aur maujooda saal donon mein Asia ki sab se kharab karkardagi dikhane wali currency ban gaya hai.
The Pakistani rupee, which spent much of 2023 and 2024 in freefall, has stabilised significantly under the IMF programme and fiscal consolidation measures. Inflation in Pakistan has fallen to 4.5 per cent in 2025, down from the hyperinflationary peaks of recent years. The combination of a stabilising Pakistani currency and a weakening Indian one has produced a reversal that few analysts predicted twelve months ago.
Why the Indian rupee has weakened
The Indian rupee’s decline has multiple causes that extend well beyond the bilateral relationship with Pakistan. Equity outflows from India exceeded an estimated $23 billion in 2026 as foreign investors pulled back from emerging markets amid rising global commodity prices and sustained tensions in West Asia. State-owned Indian banks have been selling dollars to support the rupee, a sign of intervention rather than organic strength. For the first time in years, not a single Indian company features among the world’s top 100 listed firms by market capitalisation, according to Moneycontrol, reflecting how deeply the selloff in domestic equities has cut.
The Indian government’s response has included what Prime Minister Narendra Modi described as an “austerity” posture, alongside successive fuel price increases. These measures have done little to arrest the rupee’s slide, which analysts have attributed to fundamental weaknesses in economic management alongside the external pressures of rising crude prices and a stronger dollar globally.
| May 2025 (Operation Sindoor) | 1 INR = around 3.32 PKR |
| May 2026 | 1 INR = about 2.90 PKR |
| 12-month depreciation | Nearly 13 per cent |
| 2026 alone | 6.8 per cent fall |
| INR vs USD record low | 96.47 rupees per dollar |
| India Asia currency rank | Worst performing in Asia 2025 and 2026 |
What it means for Pakistan
For Pakistan, the reversal carries both symbolic and practical weight. Symbolically, a currency that was widely mocked as worthless during Pakistan’s near-default in 2023 is now outperforming the currency of what is considered one of the world’s fastest-growing major economies. Practically, the shift affects remittances, informal cross-border trade in border communities, and the relative purchasing power of citizens on both sides.
Pakistan’s economic stabilisation has come at a significant cost. IMF conditionalities, fuel price adjustments, and tax base expansion have squeezed household incomes. The country’s nominal GDP remains at approximately $410 billion, ranking 42nd globally, against India’s position as one of the world’s top five economies. The currency movement does not change that fundamental gap. What it does reflect is the relative direction of travel of two economies at a specific moment in time.
The context that gets left out
The exchange rate shift has generated significant social media commentary in Pakistan, with some graphics circulating online describing it as evidence of a broader economic reversal. That framing requires caution. Currency movements between two countries that do not directly trade in each other’s currencies, and where cross-border commerce is severely limited by political relations, carry less practical significance than movements against a reserve currency like the dollar. Both the Indian rupee and the Pakistani rupee are priced primarily against the US dollar, and their bilateral rate is a derived calculation rather than a market signal of direct economic competition.
What the data does confirm is that India’s currency has faced genuine structural pressure over the past twelve months, that Pakistan’s stabilisation programme has produced measurable results, and that the economic consequences of Operation Sindoor extended beyond the immediate military and diplomatic sphere into financial markets on both sides of the border.
What comes next
The direction of the rupee on both sides will depend heavily on factors largely outside bilateral control. For India, the trajectory of crude oil prices, the pace of foreign equity outflows, and the Reserve Bank of India’s intervention capacity will determine whether the rupee recovers or continues to slide. For Pakistan, the sustainability of the IMF programme, the outcome of the China visit by Prime Minister Shehbaz Sharif, and the impact of CPEC Phase II investment will shape whether the stabilisation holds.
The Thursday Times will continue to track the exchange rate and the broader economic picture on both sides of the border.
Sources: The Wire, GeniusWindow, Currency.Wiki, Trading Economics, IMF World Economic Outlook April 2026, Moneycontrol. Exchange rate data sourced from publicly available currency tracking services. The Thursday Times notes that INR-PKR bilateral rates are derived calculations and that both currencies are primarily priced against the US dollar in international markets.